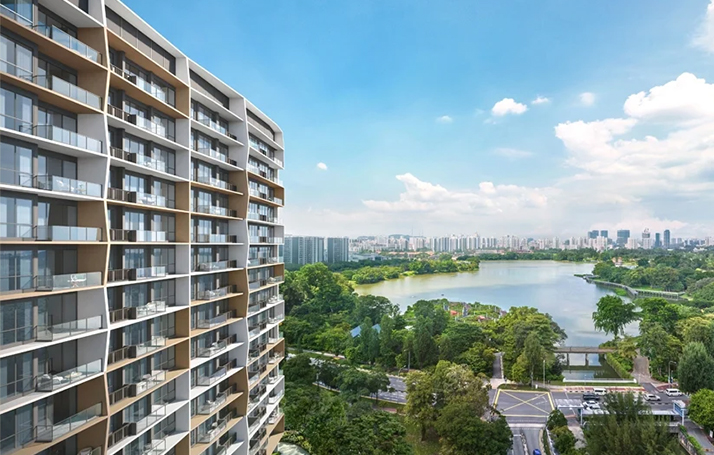
 CDL is planning to launch its 570-unit Lucerne Grand in October 2026. Located on Lakeside Drive near Jurong Lake Gardens, the rare mixed-use development is directly linked to Lakeside MRT station. (Artist’s Impression)
Hong Leong
Group Of Companies
Report
Half Year Earnings
For 2026
City Developments Limited (CDL)
CDL tripled its net attributable profit after tax and minority interest (PATMI) to S$301.6 million for the half year ended 30 June 2026 (1H 2026), compared to S$91.2 million in 1H 2025. This was primarily driven by stronger performance from the Group’s property development segment. Lumina Grand, a fully sold 512-unit Executive Condominium (EC) in Bukit Batok, obtained its Temporary Occupation Permit (TOP), in April 2026, enabling revenue and profit to be recognised in entirety under prevailing accounting policies for ECs.
The Group posted revenue of S$2.7 billion for 1H 2026, 61.1% higher than the S$1.7 billion recorded in 1H 2025. The property development segment remained the largest contributor to its revenue, with a 166.8% increase in revenue for 1H 2026, driven by Lumina Grand and further supported by Newport Residences, Norwood Grand, and Union Square Residences. Additionally, the hotel operations segment also saw a 6.4% increase in revenue, supported by a 4.9% rise in Revenue Per Available Room (RevPAR) for 1H 2026.
The Group registered a significant pre-tax profit of S$403.8 million for 1H 2026, up from S$139.9 million in 1H 2025, driven by higher revenue across all three core business segments. Profits were recognised from Lumina Grand along with other strong-performing projects such as Newport Residences, The Myst and Norwood Grand, as well as joint venture (JV) projects CanningHill Piers, Zyon Grand, The Orie and Kassia.
The hotel operations segment also reported a healthy pre-tax profit of S$42.0 million for 1H 2026, which was mainly driven by higher revenue and a net exchange gain from the appreciation of the SGD.
Investment properties were impacted by lower capital recycling gains in 1H 2026, coupled with the absence of contributions from properties that were divested in 2025. Completed divestments in 1H 2026 included Quayside Isle and the remaining strata units at Fortune Centre.
For 1H 2026, the Board has declared payment of a tax-exempt (one-tier) interim dividend of 6.0 cents per ordinary share.
Mr Kwek Leng Beng, CDL’s Executive Chairman, said, “CDL Group’s threefold increase in PATMI for 1H 2026 demonstrates the strength of our diversified portfolio. Amid an increasingly complex global environment, we remained focused on prudently managing costs and capital while continuing to strengthen our business. Our hospitality portfolio showed steady momentum with RevPAR growth across all regions, supported by the strength and quality of our global hotel assets. We will continue to take a mid and long-term view, actively managing our portfolio and capital to create sustainable value.”
Mr Sherman Kwek, CDL’s Group Chief Executive Officer, said, “The operating environment continues to be increasingly volatile, with geopolitical developments, evolving trade policies and shifting capital market conditions reshaping the landscape globally. While these factors may introduce uncertainty, our priorities remain focused on strengthening portfolio quality, enhancing earnings visibility and pursuing capital recycling initiatives. The outcome of our strategic review exercise remains on track to be announced by end-September 2026 and will clearly articulate the future strategic direction, capital allocation framework and implementation roadmap for our next phase of value creation.”
Please click here for the full CDL H1 2026 results.
CDL Hospitality Trusts (CDLHT)
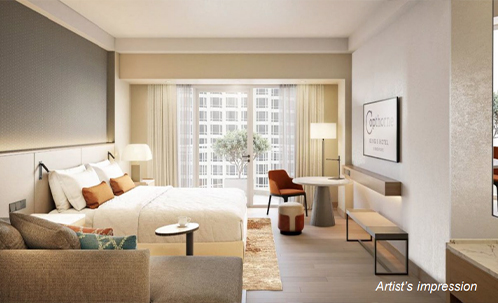 CDLHT continues to invest in asset enhancements to strengthen competitive positioning and drive value creation through asset enhancement initiatives at M Hotel, Copthorne King's Hotel, and Hilton Cambridge City Centre to support performance post-completion. Pictured is an artist’s impression of a refurbished room at Copthorne King’s Hotel; the refurbishment of 167 rooms in the main wing is scheduled to commence in 4Q 2026 in phases.
For 1H 2026, CDLHT’s gross revenue rose 1.4% year-on-year (YoY) to S$126.9 million. The conflict in the Middle East had a negative effect of varying degrees across the portfolio, with reduced air capacity from Middle Eastern carriers, increased airfares from elevated jet fuel prices, and softer corporate and leisure travel intent tempering the topline. Nevertheless, stronger operating performances from the New Zealand, Singapore, Australia, UK and Italy portfolios supported revenue growth. Net property income (NPI) grew 1.8% YoY to S$59.7 million, lifted mainly by higher earnings from the UK portfolio, Grand Millennium Auckland and the Perth Hotels.
Interest costs for 1H 2026 fell 31.9% or S$7.7 million YoY, reflecting CDLHT’s capital management initiatives and lower floating interest rates. Interest savings arose mainly from the repayment of higher-cost borrowings using the proceeds from the S$250.0 million of perpetual securities issued in November 2025 and February 2026, as well as the decline in interest rates from the levels seen in 1H 2025. Factoring in distributions to perpetual securities holders, funding costs declined 14.5% or S$3.5 million YoY.
RevPAR for the Singapore Hotels rose 4.1% YoY as Singapore’s standing as a stable gateway destination, diversified demand drivers and steady events pipeline continued to support performance amidst a broader travel moderation. NPI for the Singapore Hotels edged up 0.2% YoY.
Total distribution to Stapled Securityholders (after retention for working capital) rose 9.7% YoY to S$27.5 million for 1H 2026, while distribution per stapled security (DPS) increased 8.6% YoY to 2.15 cents, underpinned by NPI growth and lower funding costs.
Mr Vincent Yeo, Chief Executive Officer of CDLHT's managers, said, “While the protracted conflict in Iran continues to weigh on global travel, business at most of our hotels has held up relatively well. Meanwhile, lower interest rates in the first half, coupled with our capital management initiatives, yielded meaningful savings in funding costs, and we expect further funding cost savings in the second half of 2026 compared to the same period last year, following the retirement of higher-cost borrowings in earlier quarters. We are pleased to deliver higher distributions to Stapled Securityholders notwithstanding the geopolitical uncertainties weighing on global travel.
“Looking ahead, the ongoing and planned asset enhancement initiatives at M Hotel, Copthorne King's Hotel and Hilton Cambridge City Centre are expected to strengthen the competitive positioning of our portfolio. The completion of the Moxy Singapore Clarke Quay acquisition in the first half of 2027 will deepen our presence in our core Singapore market. We will also continue to pursue capital recycling opportunities to unlock underlying asset values and enhance returns.”
Please click here for the full CDLHT 1H 2026 results.
Hong Leong Asia (HLA)
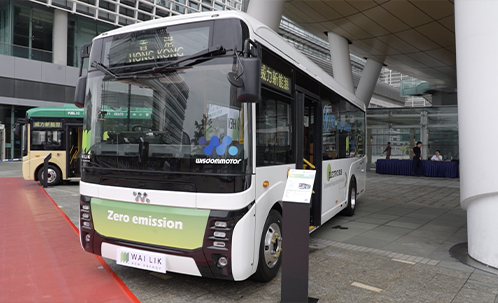 HLA has invested in higher R&D spending to strengthen its portfolio of powertrain solutions, including the development of new energy solutions such as the launch of commercial minibuses equipped with Yuchai’s YCY24-65kW Flywheel Range Extender System (YC-FRS) in Hong Kong SAR.
HLA, together with its subsidiaries (Group), a diversified Asian multinational with core businesses in powertrain solutions (Yuchai) and building materials (BMU), announced attributable PATMI of S$91.9 million for the half year ended 30 June 2026, an increase of 64.1% YoY.
The YoY increase in PATMI for 1H 2026 was driven by strong performances in Yuchai and BMU as well as positive contribution from Yong Tai Loong (Pte) Ltd. (Yong Tai Loong) acquired earlier in the year.
Group revenue increased 17.6% YoY to S$3.1 billion, lifted by the strong performance of Yuchai, underpinned by strong demand growth for power generators in the marine and power generation sector as well as exports in powertrains for trucks and industrial applications.
In China, Yuchai’s revenue of S$2.7 billion grew 16.8% YoY, with reportable segment profit after tax of S$156.7 million, up 61.8% YoY. Powertrain units sold in 1H 2026 increased 10.9% YoY to 277,684 units. Truck powertrain unit sales rose by 20.4% YoY, compared with commercial vehicle market sales growth (excluding gasoline- and electric-powered vehicles) of 5.8% YoY as reported by the China Association of Automobile Manufacturers for 1H 2026. Off-road engine unit sales performed well, with both marine and genset and industrial units showing growth of 42.0% and 15.8% YoY respectively. Yuchai’s higher gross margin was supported by an improved sales mix with higher unit sales of high horsepower engines, higher mix of export engines and improved scale savings.
In Singapore and Malaysia, BMU’s revenue was S$384.8 million, up 24.1% YoY with reportable segment profit after tax of S$56.1 million, an increase of 49.9% YoY. Demand for building materials such as precast and ready-mix concrete was strong, with continued growth in construction activities in Singapore. While higher fuel inputs due to ongoing Middle East conflict have created industry uncertainties, key project wins boosted the order book to a record level for the precast segment in 1H 2026.
Profitability of the BMU in Malaysia (Tasek) was held by improved pricing as the industry adjusted for higher fuel and logistics costs as well as healthy performance at a key associate.
The acquisition of architectural building products leader Yong Tai Loong in April 2026 has strengthened the Group’s building materials portfolio and expanded our product offering in Singapore. Riding on the back of strong construction demand from both public and private residential projects, the addition of Yong Tai Loong to the building materials portfolio positions the Group for further growth in Singapore’s built environment sector.
HLA Board of Directors is pleased to declare an interim dividend of S$0.03 per share for 1H 2026, an increase of 50% YoY.
Please click here for the full HLA H1 2026 results.
Hong Leong Finance (HLF)
 For its continued excellence, HLF received prestigious accolades including “ASEAN Finance Company of the Year” at the Asian Banking & Finance Retail Banking Awards, “Top 1000 World Bank” by The Banker, “Top 100 Most Valuable Singaporean Brand” by Brand Finance, and “SBR Technology Excellence Awards - API Financial Services” by Singapore Business Review for its enhanced vehicle loans digital platform enabler for car dealers and buyers.
HLF reported a net profit after tax of S$35.0 million for H1 2026 ended 30 June 2026, an increase of 8.8% as compared with the same period last year, driven by improved net interest margin at 1.4%.
The improved net interest margin stemmed from a significant 47.7% reduction in deposit costs, outpacing the 27.5% decline in interest yields on loans and liquid assets arising from sustained low benchmark interest rates. As a result, net interest income increased by 8.4% to $96.8 million. Fee and commission income grew 92.9% to $7.9 million for H1 2026, boosted by strong loan fee performance.
The Group maintained a strong liquidity buffer well above the regulatory Minimum Liquid Asset (MLA) and remained robust to navigate the evolving market conditions and economic uncertainties. The Group’s Capital Adequacy Ratio stood at 15.7% as at 30 June 2026, well capitalised above regulatory requirement to support lending activities and financial stability.
Looking ahead, the business operating environment is shaped by continued macroeconomic uncertainty, evolving geopolitical developments, and changing monetary policy expectations. HLF will remain focused on executing its strategic priorities to sustain profitable growth and deliver long-term value to its stakeholders while remaining resilient to volatile market conditions in an increasingly competitive financial landscape.
HLF has declared an interim dividend of 2.85 cents per share (tax-exempt one-tier) in respect of the financial year 2026.
Please click here for the full HLF H1 2026 results.
