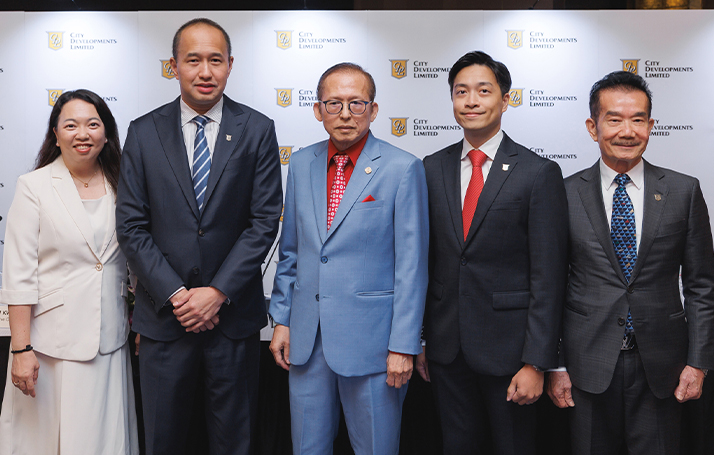
 CDL’s senior management at its 1H 2025 results briefing (L-R): Group Chief Financial Officer Ms Yiong Yim Ming; Group Chief Executive Officer Mr Sherman Kwek; Executive Chairman Mr Kwek Leng Beng; Group Chief Operating Officer Mr Kwek Eik Sheng; and Group General Manager Mr Chia Ngiang Hong.
Hong Leong
Group
Companies
Report 1H 2025
Results
City Developments Limited (CDL)
CDL recorded a revenue of S$1.7 billion and a profit after tax and non-controlling interests (PATMI) of S$91.2 million for the first half of 2025. This growth was driven by the property development segment, particularly the full profit recognition from the fully sold Copen Grand executive condominium (EC) project. Capital recycling continues to be a key focus and over S$1.5 billion in contracted divestments has been achieved YTD.
The Group’s performance was adversely affected by S$63.1 million in unrealised net foreign exchange losses, otherwise PATMI would have increased by 323% (excluding foreign exchange losses/gains)
Key highlights include:
- Property Development: Sold 903 units including ECs with a sales value of S$2.2 billion in Singapore.
- Investment Properties: Stable occupancy of 97% across its Singapore office and retail portfolio.
- Hotel Operations: The Group’s hotel RevPAR grew 0.5% to S$155.6 in 1H 2025, supported by hotel acquisitions in Australasia and rest of UK and Europe.
Mr Kwek Leng Beng, CDL’s Executive Chairman, said, “1H 2025 marked a pivotal chapter for our Group as we overcame internal challenges with tenacity and fortitude. We have put past issues behind us, emerging stronger and more unified. The Board and management are aligned and focused on effective execution and value creation. Our priority is to deliver on our commitments – strengthening our balance sheet, unlocking the potential of our portfolio and redeploying capital into higher-yielding opportunities. We remain steadfast in building a resilient and future-ready organisation, anchored in trust, performance and sustainable growth.”
Mr Sherman Kwek, CDL’s Group Chief Executive Officer, said, “Despite some instability in the earlier part of the year due to internal issues, the ensuing period has been marked by stabilisation, renewed alignment and disciplined execution. Amid ongoing macroeconomic uncertainty, the Group has taken a prudent stance on new investments while accelerating capital recycling. To date, we have secured over S$1.5 billion in contracted divestments, with more coming in the pipeline. These efforts aim to strengthen our capital position and optimise our portfolio. Looking ahead, while the operating environment remains fluid, the potential easing of interest rates offers further upside as we continue to pursue our capital recycling and fund management initiatives.”
CDL Hospitality Trusts (CDLHT)
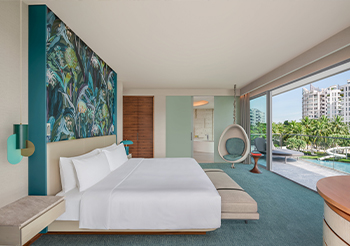 W Singapore – Sentosa Cove’s Marvelous Suite post AEI. The hotel is undertaking a phased renovation of all rooms, with estimated completion around early 2026.
For 1H 2025, CDLHT reported a 1.8% year-on-year (“yoy”) decline in gross revenue to S$125.1 million as most portfolio markets softened, except for the UK, Japan and Australia, which recorded revenue growth. The UK portfolio’s NPI was supported by the inorganic contributions from The Castings, Benson Yard and Hotel Indigo Exeter. Overall, NPI declined by 11.9% yoy to S$58.6 million, with W Hotel accounting for S$3.2 million of the S$7.9 million net NPI decline due to ongoing room renovations.
Total distribution for 1H 2025 was S$25.1 million and total distribution per Stapled Security (“DPS”) was 1.98 cents, representing a decrease of 20.2% and 21.1% yoy respectively. The decline was partly attributed to The Castings, where NPI during the ramp-up phase was insufficient to cover the associated interest costs. This, together with the decline in overall NPI and higher total interest costs contributed to the lower distribution and DPS.
Mr Vincent Yeo, Chief Executive Officer of CDLHT’s managers, said, “The unstable global macroeconomic environment significantly impacted our portfolio performance for the first half. Corporate business was markedly more subdued, partially reflecting tariff uncertainties. In the meantime, our living sector assets continue to gain traction, with Benson Yard delivering strong performance and The Castings ramping up steadily towards stabilisation. While macroeconomic uncertainty persists, we believe our core Singapore portfolio is on better footing heading into the second half of 2025, and we remain disciplined in managing both operating and financing costs.
“Our current low fixed to floating debt profile combined with our interest rate hedging strategy, positions us to benefit from a potentially more favourable rate environment. At the same time, we are committed to long-term value creation through selective asset enhancements — including ongoing upgrades at Grand Millennium Auckland and W Hotel — while continuing to see positive results from completed initiatives such as those at Ibis Perth. Capital recycling remains an integral part of our strategy to unlock value and reinforce portfolio resilience.”
Hong Leong Finance (HLF)
 HLF reported a net profit after tax of $32.2 million for the first half-year ended 30 June 2025.
The Group reported a net profit after tax of $32.2 million for the first half-year ended 30 June 2025, a decline of 38.7% as compared with the same period last year driven by compressed net interest margins at 1.3% amidst the prevailing market rate environment.
The compressed net interest margin stemmed from a significant decline in interest yields on loans and liquid assets, outpacing the reduction in deposit costs arising from falling benchmark interest rates. As a result, net interest income contracted by 20.8% to $89.2 million.
Fee and commission income edged up 2.7% to $4.1 million for the first half-year 2025, supported by healthy loan fee income.
Net allowances for loans and other financial assets were a net writeback of $6.2 million for the first half-year 2025 as compared to $2.1 million in the corresponding period. Asset quality remained stable as the Group continued to exercise prudence in its credit risk management and close monitoring of high-risk sectors with adequate loss allowances to cover the loan portfolio. The non-performing loan ratio remained low at 0.4%.
Net loan assets totaling $11,755 million as at 30 June 2025, increased by 0.8% or $87 million over the previous year’s base of $11,668 million as at 31 December 2024 and 1.9% or $217 million over corresponding period as at 30 June 2024. The loan portfolio remained largely secured.
Hong Leong Asia (HLA)
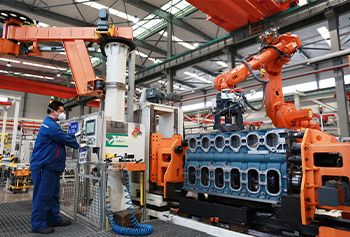 Net profit for Hong Leong Asia rises 13.1% to S$56 million in 1H 2025, led by strong growth from powertrain solutions business Yuchai.
HLA delivered 13.1% year-on-year growth in 1H 2025 attributable net profit (PATMI) of S$56 million, underpinned by strong performance from powertrain solutions (“Yuchai”) business and higher precast concrete volumes for the building materials business (“BMU”).
Group revenue for 1H 2025 increased by 25.7% YoY to S$2.8 billion, led by strong growth from Yuchai. Yuchai’s 1H 2025 revenue grew 30.8% YoY to S$2.5 billion, with reportable segment profit after tax of S$96.8 million, up 56.4% YoY. Powertrain units sold in 1H 2025 increased 29.9% YoY to 250,396 units with robust sales for the data centre sector contributing to the strong results. Notwithstanding a weak domestic market, export sales volumes from OEM customers were notable strong in 1H 2025 with Yuchai gaining market share across all segments.
For overseas market development, Yuchai’s subsidiary in Thailand and a strategic cooperation with Kim Long Motor Hue, a subsidiary of Vietnam's FUTA Group, have deepened Yuchai’s market penetration into the growing ASEAN market.
In Singapore and Malaysia, BMU’s revenue declined 3.5% YoY to S$310.2 million, with reportable segment profit after tax of S$37.5 million, a decline of 10.5% YoY. This is largely due to lower sales volume for ready-mix concrete, which was partially offset by higher precast concrete sales volume in Singapore. Despite the volume drop caused mainly by delays in capacity replacement, order book for building materials grew in 1H 2025, supported by the rise in commercial and public housing projects. Profitability for the building materials business in Malaysia was lifted by operational efficiency gains in its ready-mixed operations and improvements at its key associate.
HLA declared an interim dividend of S$0.02 per share for 1H 2025, doubling the interim dividend of S$0.01 per share for 1H 2024.
