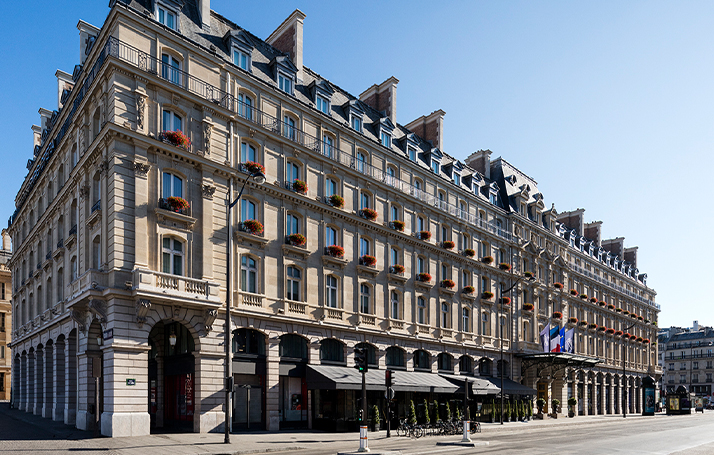
 In May 2024, CDL acquired the 268-room Hilton Paris Opéra for €240 million (approximately S$350.2 million). This iconic, freehold hotel has seen strong demand with notable high occupancy and average room rate (ARR), especially during the Paris 2024 Olympics.
A Snapshot
Of Hong Leong
Companies’
2024 Half
Year Results
City Developments Limited (CDL)
CDL achieved a 32.0% increase in net attributable profit after tax and non-controlling interest (PATMI) of S$87.8 million (1H 2023: S$66.5 million). The increase was supported by divestment gains as part of the Group’s capital recycling efforts. Notably, results in the previous corresponding period in 2023 included the full recognition of revenue and profits from an Executive Condominium (EC) project, Piermont Grand, of which the Group owns 60%.
The Group achieved a lower revenue of S$1.6 billion for 1H 2024 (1H 2023: S$2.7 billion) as 1H 2023 included a S$1.0 billion contribution from Piermont Grand, which was recognised in its entirety when the EC project obtained its Temporary Occupation Permit (TOP) in January 2023.
The investment properties and hotel operations segments saw a 21.3% and 10.8% increase in revenue for 1H 2024, respectively. The increase in the investment properties segment was mainly driven by the investment properties acquired in 2023, such as St Katharine Docks and the living sector assets.
Revenue for the hotel operations segment continued to increase steadily, with Revenue Per Available Room (RevPAR) growth across most regions further bolstered by the addition of the newly acquired Sofitel Brisbane Central hotel in December 2023 and Hilton Paris Opéra hotel in May 2024.
The Group registered a pre-tax profit of S$155.4 million for 1H 2024 (1H 2023: S$179.5 million) largely due to higher financing costs and lower profits from the property development segment.
The property development segment registered substantially lower profits in 1H 2024 vis-à-vis 1H 2023 due to the timing of profit recognition. Unfortunately, construction delays for certain projects resulted in lower-than-expected profit contribution in 1H 2024, whereas in 1H 2023, the Group recorded a substantial profit contribution from Piermont Grand and another completed joint venture (JV) project, Boulevard 88, which obtained its TOP in April 2023.
Higher financing costs were also recorded in 1H 2024 for this segment relating to projects that have yet to be launched, including Union Square Residences, Norwood Grand in Woodlands and the Lorong 1 Toa Payoh site.
The investment properties segment is the largest contributor to pre-tax profits for 1H 2024, supported by divestment gains on the sale of strata units in Citilink Warehouse Complex, Cititech Industrial Building and Fortune Centre, along with contributions from several acquisitions.
The Group’s hotel operations segment also reported a healthy pre-tax profit for 1H 2024 and positive EBITDA for all regions, reflecting continued recovery momentum.
As of 30 June 2024, the Group maintained its robust capital position with cash reserves of S$1.7 billion1, and cash and available undrawn committed bank facilities totalling S$3.7 billion.
After factoring in fair value on investment properties, the Group’s net gearing ratio stands at 69% (FY 2023: 61%), following the acquisition of the Hilton Paris Opéra hotel and three Japan Private Rented Sector (PRS) properties, coupled with the share buyback of CDL’s ordinary shares and preference shares as well as dividend payments.
For CDL’s full 1H financial report, please visit here.
1Net of overdraft
CDL Hospitality Trusts (CDLHT)
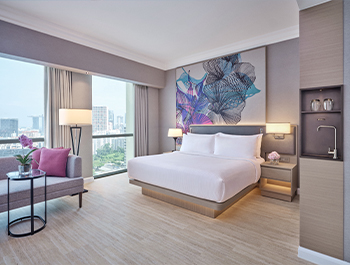 Leading the charge towards our commitment to zero single-use plastics by 2050, Grand Copthorne Waterfront Hotel has introduced an in-room water filtration system in its guest rooms, reducing single-use plastic waste generated from traditional bottled water consumption by 20%.
For 1H 2024, NPI increased 5.9% (or S$3.7 million) year-on-year (“yoy”) to S$66.5 million in tandem with the 6.8% yoy increase in gross revenue. NPI improvement was recorded in almost all the portfolio markets, except the UK market which was flat and New Zealand market which was down yoy. Although the pent-up demand post-pandemic tapered off in most markets, RevPAR growth for 1H 2024 was recorded across virtually all portfolio markets.
Interest costs for 1H 2024 increased yoy, mainly due to higher funding costs on the floating rate loans and interest expenses from additional amounts drawn. In 1H 2024, CDLHT increased one of its committed sustainability-linked revolving credit facilities by an additional S$50.0 million, bringing the total amount of sustainability-linked facilities to S$355.9 million.
The Singapore Hotels’ performance in the second quarter was more muted as there were several weekday public holidays, weaker materialisation from keynote events, an increase in hotel supply and the oil spill near Sentosa (affecting W Hotel) which caused RevPAR to post a slight 0.9% drop compared to a year ago. 1H 2024 RevPAR for the Singapore Hotels increased by 7.7% yoy, driven by occupancy growth. NPI for the Singapore portfolio (including Claymore Connect) for 1H 2024 grew in tandem by 6.8% or S$2.6 million yoy.
Total distribution to Stapled Securityholders (after retention for working capital) for 1H 2024 remained relatively stable at S$31.4 million and DPS was 2.51 cents, flat yoy.
As at 30 June 2024, CDLHT had a gearing of 37.7% and debt headroom of S$783.3 million (at 50% gearing limit), with cash reserves of S$64.9 million and S$648.5 million1 of credit facilities.
For CDLHT’s full 1H financial report, please visit here.
1Comprising approximately S$237.9 million committed unsecured revolving credit facilities, S$10.6 million undrawn committed term loan facility and S$400.0 million uncommitted bridge loan facilities
Hong Leong Finance (HLF)
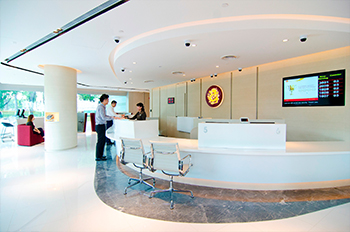 As part of its ongoing journey to meet the evolving needs of its customers, Hong Leong Finance launched HLF Digital, a mobile device app and web portal which provides customers with convenient 24/7 access to their accounts and a range of related financial services.
HLF reported a net attributable profit of S$52.6 million for first half-year ended 30 June 2024, grew 12.9% or S$6 million from the same period last year, driven by higher net interest income at an expanded net interest margin of 1.6%.
Net interest income rose 11.1% to S$112.7 million on the back of improved assets yields, outpacing the elevated funding cost year-on-year.
Fee and commission income declined by 9.2% to S$4.0 million for first half-year 2024 on subdued large mortgage lending activities in financial markets.
Total operating expenses increased slightly by 5.6% to S$55.7 million for first half-year 2024 mainly due to higher staff cost from annual salaries increment and resources to enhance regulatory compliance and risk management with our focus in business transformation. It was partially offset by the broad-based decline in the operating expenses with tightened cost control.
Net allowances for loans and other financial assets were a net write-back of S$2.1 million for first half-year 2024 as compared to S$2.7 million in the corresponding period. This included a reversal of S$1.6 million in allowances for non credit-impaired loans with improved risk parameters and a reversal of S$0.2 million in allowances for credit-impaired loans with loan repayment. Asset quality remained resilient as the Group continued to exercise prudence in its credit risk management and underwriting parameters with adequate loss allowances to cover the loan portfolio. The non-performing loan ratio remained stable at 0.7%.
Net loan assets totalling S$11,538 million as at 30 June 2024, down by 1.0% or S$121 million over the previous year’s base of S$11,659 million as at 31 December 2023 and 1.1% or S$127 million over corresponding period as at 30 June 2023. The loan portfolio remained largely secured.
In tandem with the reduced loan assets, deposits and balances of customers decreased to S$12,153 million as at 30 June 2024, representing a decrease of 3.9% or S$495 million over the previous year’s base of S$12,648 million as at 31 December 2023 and 0.1% or S$11 million over corresponding period as at 30 June 2023.
Cash and cash equivalents including statutory deposit with the Monetary Authority of Singapore (“MAS”) together with Singapore Government debt securities, MAS Bills and MAS FRN held as liquid assets amounted to S$2,915 million as at 30 June 2024 (31 December 2023: S$3,209 million). The Group maintained liquidity above regulatory Minimum Liquid Asset (“MLA”) and remained highly liquid to maneuver the market uncertainties.
Group shareholders’ funds as at 30 June 2024 totalled S$2,073 million (31 December 2023: S$2,060 million) with net asset value at S$4.62 per share (31 December 2023: S$4.59 per share). The Group’s Capital Adequacy Ratio stood at 16.9% as at 30 June 2024, well capitalised above regulatory requirement to support lending activities.
For HLF’s full 1H financial report, please visit here.
Hong Leong Asia (HLA)
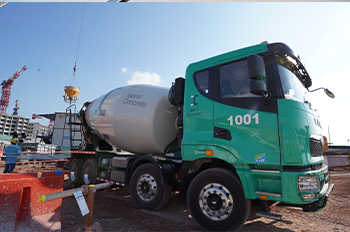 Demand for building materials in ready-mix concrete continued to be strong, led by public sector projects in Singapore. Both powertrain solutions and building materials units registered robust growth.
HLA achieved attributable net profit of S$49.5 million for the half year ended 30 June 2024 (“1H2024”).
Group revenue increased 8.5% yoy to S$2.3 billion, with robust growth at both powertrain solutions (“Yuchai”) and building materials units (“BMU”). The Group’s profitability was lifted
by strong performance at both Yuchai and BMU on the back of improving market conditions
in Singapore, Malaysia and China.
In China, Yuchai's revenue grew 9.3% yoy to S$1.9 billion, with reportable segment profit after
tax of S$61.9 million, up 28.8% yoy. Total number of engines sold in 1H 2024 increased
16.3% yoy to 192,743 units led by truck and bus/industrial engines sales volume growth.
Higher gross margins were also realised by ongoing cost reduction efforts and better sales
mix toward heavy-duty vehicle engines and industrial engines.
In Singapore and Malaysia, BMU revenue grew 5.0% yoy to S$321.5 million, with reportable
segment profit after tax of S$42.0 million, representing growth of 35.2% yoy. Demand for
building materials in ready-mix concrete continued to be strong, led by public sector projects in Singapore. HLA’s prefabrication business in R3 Precast was affected by the slow project offtake in the industry although the order book continues to grow.
In Malaysia, notwithstanding challenges in rising energy and transportation costs with the removal of diesel subsidies, Tasek’s profitability was lifted by higher sales volumes and selling prices, bolstered by the softening of coal prices.
The Company is pleased to announce an interim dividend of S$0.01 per share.
Market Outlook
In China, Yuchai is doing well with strong unit sales growth in almost all segments. The key
statistics from China Association of Automobile Manufacturers’ Report shows commercial
diesel vehicles unit sales growing at 4.4% yoy in 1H 2024. In July 2024, China’s National
Development and Reform Commission announced a RMB 300 billion stimulus programme to
encourage businesses and consumers to scrap old vehicles and equipment and replace them for newer versions. The stimulus programme is seen as a net positive for the powertrain
industry and is likely to be felt as business confidence improves and the programme is drawn
down. In the meantime, Yuchai continues to invest in R&D initiatives to improve its powertrain
portfolio, including the development of new energy solutions.
In Singapore, BMU in Singapore expects its order books in the Precast and Ready-Mix
Concrete segments to continue to grow from public and private sector projects. This is in line
with the Building and Construction Authority’s projection of the total value of construction
contracts to be awarded in 2024. Our innovation with the introduction of the larger 12 cubic
metre ready-mix concrete trucks to counter a shortage of drivers has improved our operational efficiency and productivity gains.
In Malaysia, BMU in Malaysia (“Tasek”) expects demand to continue to improve with the
increased infrastructure development expenditure. Overall costs are expected to rise with the recent removal of diesel subsidies. Tasek is focused on improving its operational efficiency and increasing the use of recycled materials as well as alternative raw materials and fuels in our ongoing efforts to be more sustainable.
For HLA’s full 1H financial report, please visit here.
