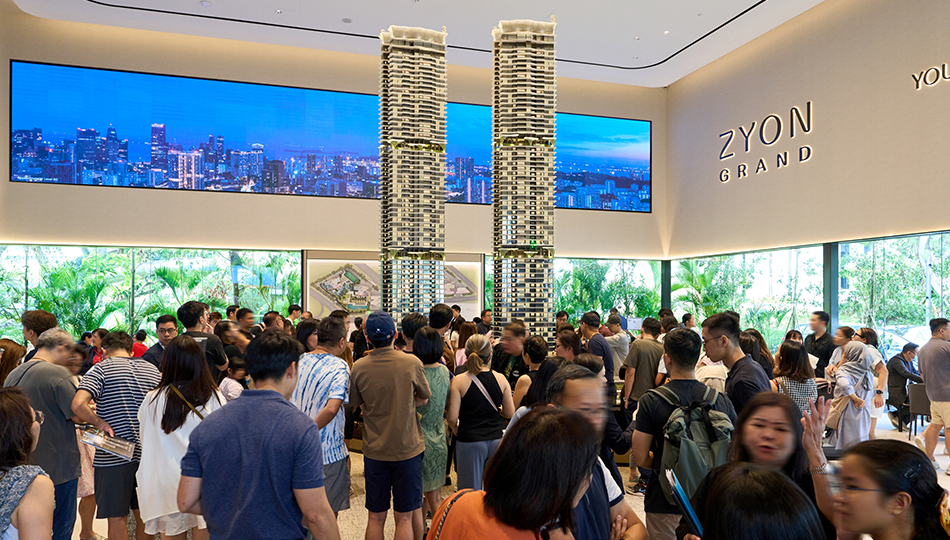
 In 2025, CDL achieved record residential sales value of S$4.35 billion in Singapore. The strong performance in 2025 was driven by two successful launches, including the 706-unit Zyon Grand, which is 87% sold to date.
Hong Leong
Group Of Companies
Report
Full Year Earnings
For 2025
City Developments Limited (CDL)
CDL tripled its net profit after tax and non-controlling interest (PATMI) to S$629.7 million for the full year ended 31 December 2025 (FY2025) compared to S$201.3 million in FY2024.
The notable performance was primarily driven by robust residential sales in Singapore and strong capital recycling gains, notably the sale of the Group’s 50.1% stake in the South Beach mixed-use development in Singapore in 2H 2025. The stellar results for FY2025 reflect CDL’s strong execution and disciplined focus on capital recycling, achieving approximately S$2 billion in contracted divestments across various geographies and asset classes.
The Group posted revenue of S$3.6 billion for FY2025, an increase of 9.7% (FY2024: S$3.3 billion). The property development segment was the largest contributor to revenue growth, rising 24.1% for FY2025, supported by higher contributions from Singapore projects such as The Myst, Norwood Grand and Union Square Residences, as well as by the sale of the Ransome’s Wharf site in London and the office component of Suzhou Hong Leong City Center in China.
Revenue from the investment properties segment grew 2.7% in FY2025, driven by completed asset enhancement initiatives (AEIs) at City Square Mall in Singapore and Jungceylon Shopping Center in Phuket. Additionally, the hotel operations segment also saw a 1.7% increase in revenue and a 1.3% rise in Revenue Per Available Room (RevPAR) for FY2025.
The hotel operations segment also reported a healthy pre-tax profit of S$256.0 million for FY2025, bolstered by capital recycling gains from the sale of JW Marriott Hotel Singapore South Beach and Comfort Inn Near Vail Beaver Creek in the US.
Mr Kwek Leng Beng, CDL’s Executive Chairman, said, “Despite macroeconomic challenges, the CDL Group delivered a strong set of results for FY2025. The tripling of PATMI underscores the resilience of our core business segments and the tangible progress we have made in sharpening execution, strengthening capital discipline and crystallising value across our portfolio. With a strong foundation, renewed focus and clear priorities, the Group is poised to build on this momentum and continue creating long-term value for our shareholders.”
Mr Sherman Kwek, CDL’s Group Chief Executive Officer, said, “2025 was a year of reflection, resilience and disciplined execution for the Group amid a challenging environment with ongoing macroeconomic uncertainties. Despite these headwinds, we stayed focused on advancing our strategic priorities, with strong residential sales in Singapore and accelerated capital recycling driving a significant uplift in our earnings. To maximise shareholder returns, we are actively reviewing our growth strategy, portfolio structures and capital allocation priorities. We have taken decisive steps to unlock value from mature and non-core assets while selectively redeploying capital to drive growth. Looking ahead, the Group enters its next phase of growth with renewed vigour. As we embark on our value creation journey, we are well positioned to deliver sustainable growth and maximise returns for all shareholders.”
To better align with shareholders’ interests and enhance transparency and clarity of shareholder returns, the CDL Board is enhancing its dividend policy and intends to declare ordinary cash dividends at least once annually, with a payout ratio of minimally 35% based on reported PATMI. The Group's financial performance, projected cash flow, capital requirements for business growth and external factors will be considered when determining the dividend payout.
For FY2025, the Board recommends a final ordinary dividend of 25.0 cents per share. Together with the special interim ordinary dividend of 3.0 cents per share paid in September 2025, the total ordinary dividend for FY2025 amounts to 28.0 cents per share, representing a dividend payout ratio of 40%.
Please click here for the full CDL FY2025 results.
CDL Hospitality Trusts (CDLHT)
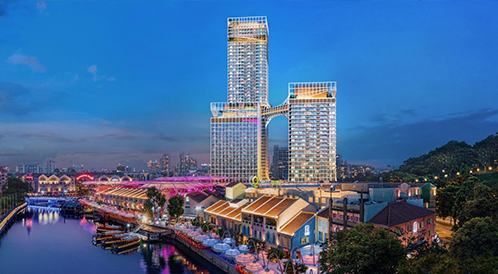 RevPAR for the Singapore hotels rose 1.6% YoY in 2H 2025, driven by increased demand supported by major events such as the World Aquatics Championships, Formula 1 Singapore Grand Prix, and concerts (e.g. Blackpink). Looking ahead to FY2026, Moxy Singapore Clarke Quay, a 475-key hotel, is projected to obtain its temporary occupation permit (TOP) around the end of 2026.
For FY2025, CDLHT’s gross revenue increased by 2.8% (S$7.3 million) YoY to S$267.6 million, driven by growth in the UK, Japan and Australia portfolios. The UK portfolio continued to benefit from inorganic contributions from The Castings (UK BTR), Benson Yard (UK PBSA) and Hotel Indigo Exeter. These contributions helped to partially offset softer trading performance in other markets. Net property income (“NPI”) declined by 4.1% to S$129.7 million YoY, reflecting a moderation in RevPAR across the portfolio and higher operating costs. A significant portion of the NPI variance was due to temporary disruptions from the renovation works at W Hotel and Grand Millennium Auckland, whereby their collective overall shortfall contributed about S$5.9 million to the overall YoY reduction. Excluding these two hotels, the Group’s gross revenue would have grown by 7.0% (or S$14.1 million) YoY, and NPI would have reported an increase of 0.3% YoY for FY2025.
Its living sector assets delivered the first full year of income, contributing S$8.2 million in NPI. In 2026, The Castings is poised to progress beyond its initial gestation phase, supporting income ramp-up, while Benson Yard will continue to benefit from stable demand.
Total distribution to Stapled Securityholders (after retention for working capital) for FY2025 was S$60.9 million and DPS was 4.80 cents, representing a decrease of 8.9% and 9.8% YoY respectively, due to the decline in overall NPI across the portfolio.
As at 31 December 2025, CDLHT’s total investment properties and property, plant and equipment value (“Total Portfolio Value”) increased by S$27.7 million or 0.8% YoY to S$3.4 billion.
Mr Vincent Yeo, Chief Executive Officer of CDLHT’s managers, said, “2025 was a year of transition for CDLHT. Income from two of our major assets was impacted as they completed their multi-year renovation programmes. During the year, SGD interest rates also moderated from elevated levels at the start of the year. While trading conditions in our key Singapore market were softer in the first half, performance improved in the second half. Financial management was a key priority in 2025, and the issuance of S$150.0 million in perpetual securities represents a proactive step in optimising our capital structure, strengthening the balance sheet and lowering funding costs.”
Please click here for the full CDLHT FY2025 results.
Hong Leong Asia (HLA)
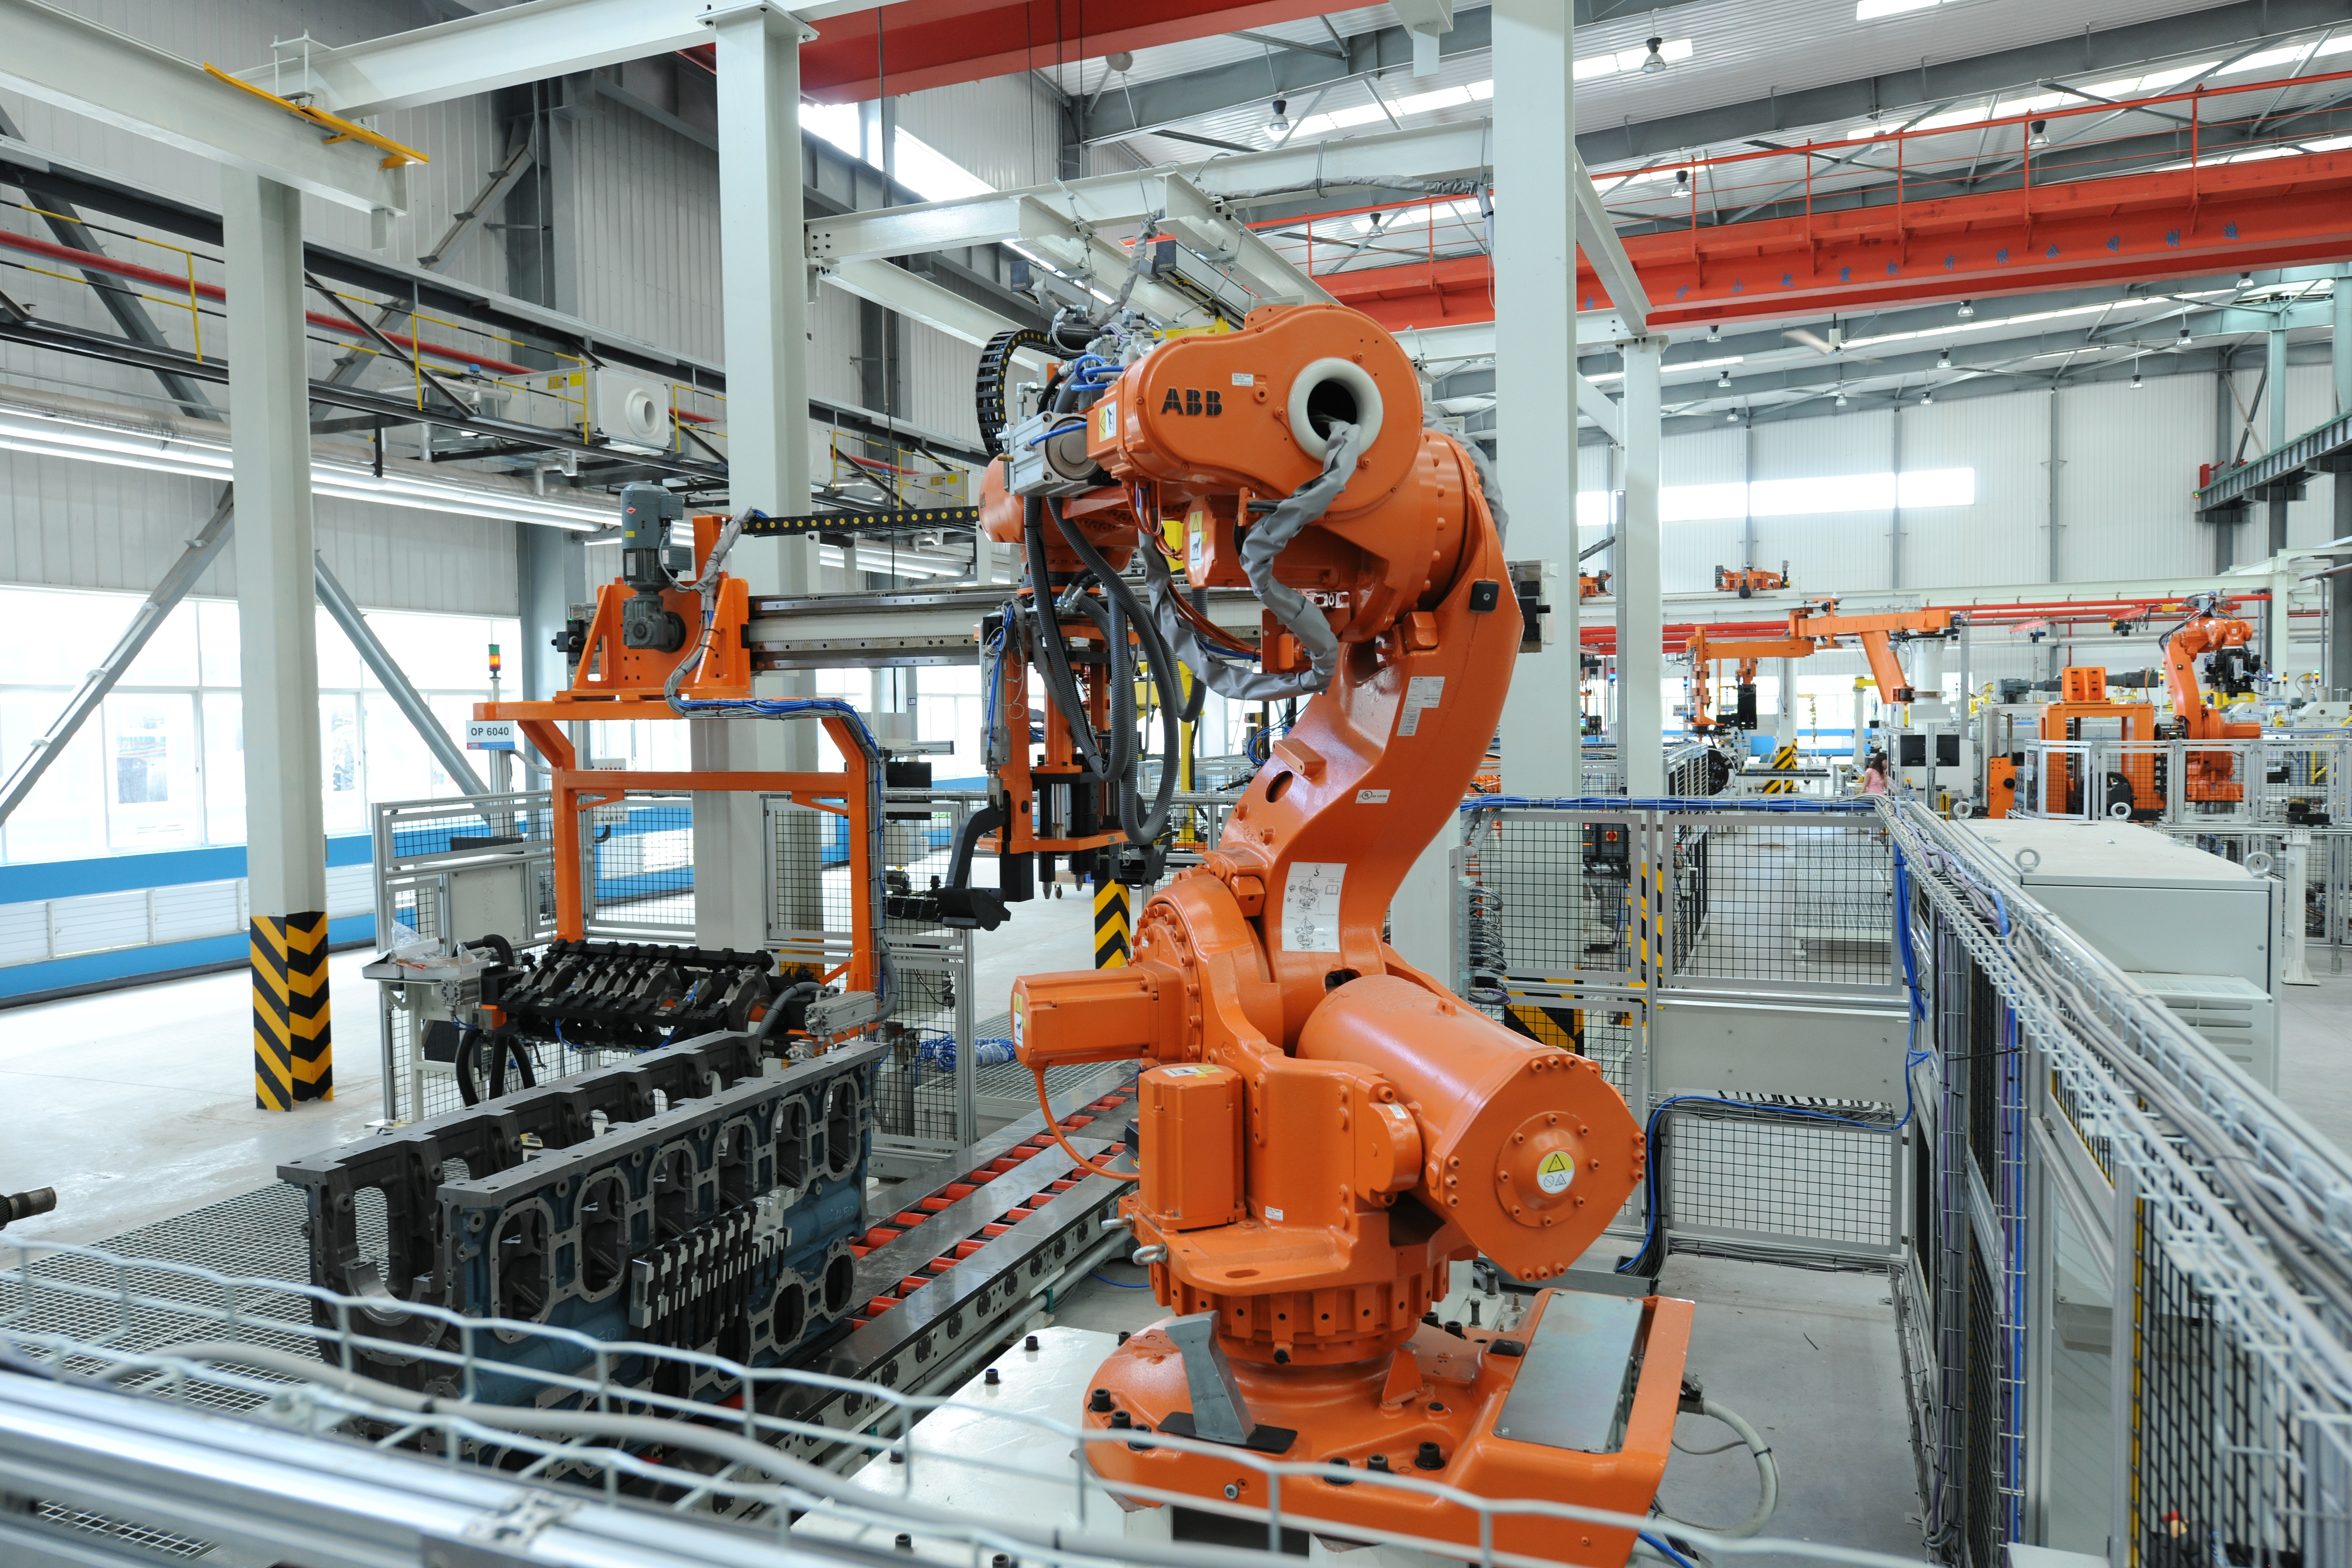 Building on its momentum, the Group continues to invest in research and development (R&D) initiatives to improve its powertrain solutions as well as new batching plants, automation technologies and larger concrete mixer trucks to improve operational efficiencies within the building materials segment.
HLA recorded a net profit of S$112.8 million for the FY2025, a 28.5% increase from FY2024. Group revenue rose by 22% YoY to S$5.2 billion. The growth was largely contributed by the powertrain solutions’ ("Yuchai") performance in the marine and power generation sectors, and improved precast volume from the building materials unit ("BMU").
Earnings per share for FY2025 stood at 15.08 cents, up from the 11.74 cents reported in the same period a year ago.
In China, Yuchai’s revenue grew 26.3% YoY to S$4.5 billion with 461,309 powertrain units sold in FY2025, up 29.4%. Overall, Yuchai performed well in the truck and bus segments which grew 42.8% YoY while the industrial and marine and genset segments grew 24.0% YoY. High horsepower powertrains units for data centres also grew strongly. Yuchai’s strong performance was also attributed to its higher gross margin driven by improved scale, ongoing cost reduction efforts and a change in sales mix with higher sales units of heavy-duty and high horsepower powertrains.
In Singapore and Malaysia, BMU’s revenue grew 4.9% to S$682.7 million in FY2025. The Precast business in Singapore reported strong performance amid continued growth in HDB-related construction activities while the ready-mixed concrete (“RMC”) segment was impacted by plant capacity adjustments earlier in the year. Overall, the Precast order book benefitted from a strong continued demand while the RMC order book caught up in the second half of the year. In Malaysia, Tasek’s profitability was supported by improved pricing and lower energy input costs as well as better performance contributed by a key associate.
The Board of Directors has proposed a final dividend of 3 cents per share. Together with the interim dividend paid of 2 cents per share, the Group has increased its dividend by 25% to 5 cents per share for FY2025.
Looking ahead, while challenges from volatile input costs and continued supply chain disruptions are expected, the Group remains focused on strengthening order books, improving operational efficiencies and managing costs down to stay relevant and resilient. Barring unforeseen circumstances, the Group expects its businesses to deliver satisfactory results in 2026.
Please click here for the full HLA FY2025 results.
Hong Leong Finance (HLF)
 With rising digital threats and financial crime, HLF bolstered anti-scam policies, technology risk management and third-party risk oversight, expanded staff training and drove community outreach with the Singapore Police, alongside customer education across multiple touchpoints.
HLF reported a net profit of S$62.7 million for FY2025 amidst an environment marked by global uncertainties and a declining benchmark interest rate cycle, which moderated its earnings. However, building on its recent momentum, HLF made progress in digital transformation, growth initiatives, security, risk management, workforce development and sustainability, to enhance long-term value.
HLF’s vehicle loans digital platform was awarded ‘Best Automobile Financing Product’ at The Asian Banker Global Excellence in Retail Finance Awards, and the Singapore Business Review Technology Excellence Awards. In the electric cars segment, HLF saw a 13% YoY increase in the amount of loans processed.
Net loan assets totalled S$12.1 billion, a rise of 3.7% from S$11.7 billion. Fee and commission income increased by 81.3% to $14.7 million, from S$8.1 million, driven by increased property financing activities amid improving market sentiment.
To better support the evolving needs of Small and Medium-sized Enterprises (SMEs), HLF introduced bundled financing that pairs Commercial Property Loans (CPLs) with Working Capital Loans. This provides SMEs with long-term property financing alongside short-term working capital liquidity within a single package, enhancing funding agility and enabling more sustainable business expansion.
HLF has proposed a final dividend of 6.15 cents per share.
The outlook for the global economy remains tempered by geopolitical uncertainties and trade-related frictions. At the same time, the continued acceleration of digitalisation brings heightened cybersecurity and operational risks.
HLF Chairman, Mr Kwek Leng Beng, said, "Notwithstanding the challenges, we remain confident in our ability to deliver enduring value to our stakeholders. Our disciplined risk management and sustained investments in digital innovation, security and workforce capability provide a strong platform for continued growth. With a clear strategic direction and a resilient foundation, we have confidence in managing uncertainties and capturing opportunities ahead.”
Please click here for the full HLF FY2025 results.
