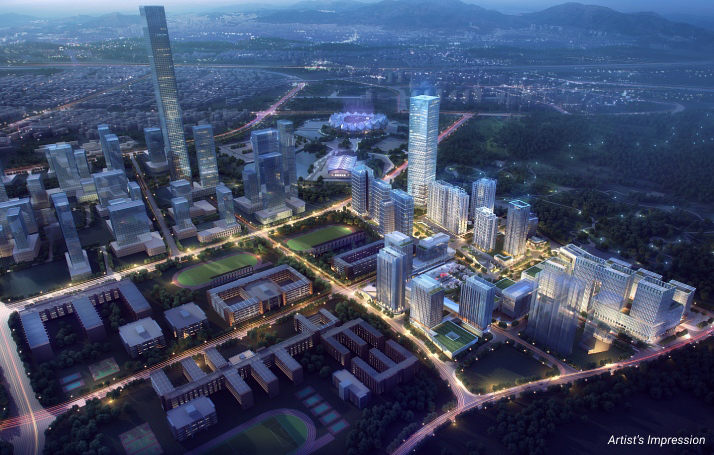
 In its first major corporate action since forming a special working group to improve liquidity of Sincere Property Group, CDL acquired an effective 55% stake in Shenzhen Longgang Tusincere Tech Park, a large-scale development in China’s high-growth “Silicon Valley”.
Hong Leong
Group Companies
Report FY 2020
Results
City Developments Limited (CDL)
With the protracted COVID-19 global pandemic adversely impacting its business and operations and a challenging operating real estate environment in China, CDL reported a loss after tax and non-controlling interest of S$1.9 billion for its second half (2H 2020) and S$1.9 billion for the year ended 31 December 2020 (FY 2020) (2H 2019: PATMI of S$202.6 million; FY 2019: PATMI of S$564.6 million).
Excluding one-off, non-cash impairments of S$1.78 billion for losses attributable to its joint venture investment in Sincere Property Group in China, impairment losses for CDL’s hotels and investment properties of S$99.5 million and allowance for foreseeable losses for development projects of S$35.0 million, CDL would have registered a profit before tax of S$83.0 million for 2H 2020 and S$120.8 million for FY 2020 (2H 2019: S$317.0 million; and FY 2019: S$805.5 million).
The Group’s revenue for 2H 2020 declined by 43.5% to S$1.0 billion (2H 2019: S$1.8 billion) and 38.5% to S$2.1 billion for FY 2020 (FY 2019: S$3.4 billion). While all segments were impacted, the Group’s hotel operations segment accounted for 81% of the decline, as the pandemic continued to spread with resurgence in some cities even amid border restrictions, lockdowns and other measures to contain the spread of the virus.
Despite the unprecedented set of results, the Group remains confident to weather the combined challenges with its strong fundamentals and financial strength. Its financial position remains robust with sufficient liquidity to meet its operational needs and financial commitments. As at 31 December 2020, the Group has cash reserves of S$3.2 billion. It maintains a strong liquidity position comprising cash and available undrawn committed bank facilities totalling S$5.2 billion. Net gearing ratio after factoring in fair value on investment properties stands at 62%.
Please click here for CDL’s FY 2020 financial statement.
CDL Hospitality Trusts (CDLHT)
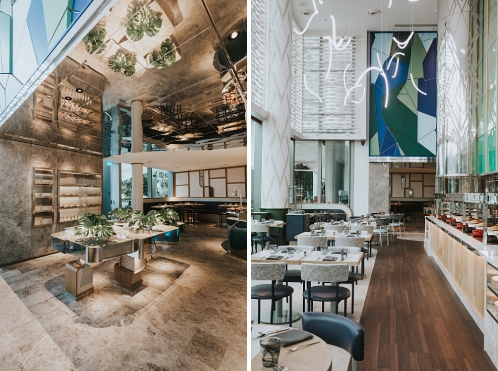 The renovation project at W Singapore – Sentosa Cove’s all-day dining restaurant, “the kitchen table”, was completed in December 2020. Seating capacity has increased from 140 to 234, with new furnishings to improve the overall guest experience.
The unprecedented COVID-19 pandemic continued to have a profound impact on the Group’s overall performance in 2H 2020. With the exception of five of CDLHT’s Singapore Hotels and the New Zealand Hotel, which were supported by demand for accommodation facilities used for isolation purposes, most of the Group’s hotels were operating at mid to low occupancies. While there was inorganic net property income (NPI) contribution from W Singapore – Sentosa Cove (acquired 16 July 2020), this was more than offset by the absence of contribution from Novotel Singapore Clarke Quay (NCQ) and Novotel Brisbane (divested on 15 July 2020 and 30 October 2020 respectively).
Accordingly, total NPI for 2H 2020 declined by 46.2% year-on-year (yoy) to S$39.6 million. The Group’s results were partially insulated by substantive rent contribution from the Singapore, New Zealand and Australia hotels amounting to S$47.8 million (inclusive of S$22.4 million fixed rent).
Total distribution to Stapled Securityholders (after retention for working capital) was S$42.1 million, while total distribution per Stapled Security (after retention) (DPS) was 3.44 cents for 2H 2020, a decrease of 28.7% and 29.2% yoy respectively. The reduction in total distribution following the decline in overall NPI was mitigated by a capital distribution of S$20.0 million which relates to a partial distribution of the proceeds from the divestment of NCQ during the year.
For FY 2020, NPI decreased 50.9% yoy to S$69.3 million. Total distribution to Stapled Securityholders (after retention for working capital) for FY 2020 was S$60.4 million (including the S$20.0 million capital distribution) and DPS was 4.95 cents, a decrease of 44.8% and 45.1% yoy respectively.
Please click here for CDLHT’s FY 2020 financial statement.
Hong Leong Finance (HLF)
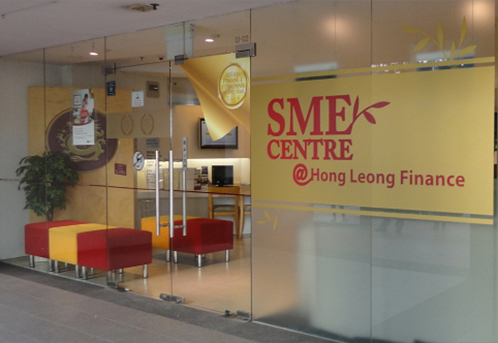 Hong Leong Finance posted a net profit of S$63.91 million for FY 2020. Pictured above is the SME Centre @ Hong Leong Finance at Balestier.
HLF reported decline in net profit of 38% to S$63.91 million for the financial year ended 31 December 2020, driven by compressed earnings and conservatively build-up of loan loss allowances. The group reported profit from operations before allowances of S$82.4 million for the year, down 34.3% due to the recession.
Net interest income fell 27.2% to S$146.85 million due to compressed net interest margins as the dip in interest yields outweighed the savings from the lower cost of funds given the sustained low interest rates environment. Higher general loan loss allowances were set aside against inherent credit risk amid uncertainties arising from the pandemic.
Earnings per share worked out to 14.28 Singapore cents, down from 23.09 cents a year ago. The board proposed a final dividend of 5.5 Singapore cents per share, down from 10 cents per share last year. This is in line with the recommendation from the Monetary Authority of Singapore for finance companies to cap their total dividends per share for FY 2020 at 60% of FY 2019’s level. Subject to shareholders' approval at an upcoming annual general meeting in April, the dividend will be paid on May 25.
“We are cautiously optimistic that the operating environment for 2021 will improve with the containment of the pandemic both globally and domestically, mainly because of promising vaccine developments,” said HLF Chairman Mr Kwek Leng Beng.
Please click here for HLF’s FY 2020 financial statement.
Hong Leong Asia (HLA)
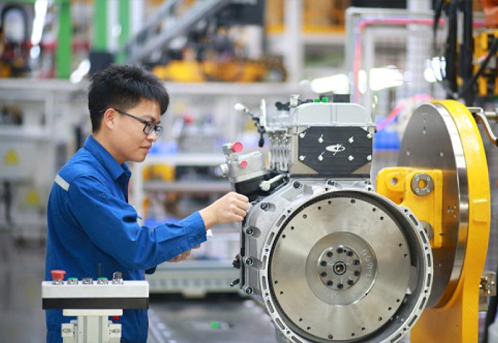 For FY 2020, China Yuchai saw higher engine sales in heavy-duty and medium-duty truck segments and off-road segments, which contributed to the 15.6% increase in revenue for the Diesel Engines Unit.
HLA recorded a 9.8% increase in revenue to S$4.496 billion for the year ended 31 December 2020. This was mainly due to higher revenue recorded by the Diesel Engines Unit (“Yuchai”) which was partially offset by the revenue decline of the Building Materials Unit (“BMU”).
Yuchai’s revenue increased $553.0 million or 15.6% as compared to FY2019, due to higher engine sales in the heavy-duty and medium-duty truck segments and off-road segments, particularly agricultural engines. Number of engines sold was 430,320 compared to 376,148 units in FY2019. BMU’s revenue decreased $142.8 million or 28.2% as compared to FY2019 as both its Singapore and Malaysian operations were affected by disruption to business activities resulting from the COVID-19 pandemic.
Net profit from continuing operations attributable to the owners of the Company was $45.3 million in FY 2020, comparable to $45.9 million in FY 2019. Profit attributable to the owners of the Company for FY2020 increased by $12.3 million to $46.7 million, as compared to $34.4 million for FY 2019.
Earnings per share is 6.25 Singapore cents, up from 4.61 cents a year ago. The board has proposed a final dividend of 1.0 Singapore cents per share, which will be paid on 18 May 2021 subject to shareholders’ approval at the upcoming annual general meeting.
“The Group is cautiously optimistic that performance will improve this year. With our conservative balance sheet and net cash position, the Group should be able to meet the challenges and capture the opportunities ahead, post-COVID,” said HLA in its results announcement.
Please click here for HLA’s FY 2020 financial statement.
First Sponsor Group Limited
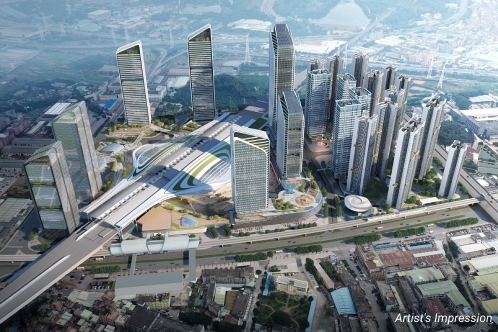 First Sponsor is optimistic about the Humen Transit-oriented Development mega project with one million square metres gross floor area acquired in late June 2020. Its first sales launch is expected to be in second half of 2021.
First Sponsor Group posted 92.7% drop in net profit to S$6.9 million for its fourth quarter ended Dec 31, 2020, from S$94.9 million a year ago. Its revenue slide 73.5% on lower revenue from the sale of properties, rental income from investment properties, hotel operations and revenue from property financing.
Revenue for Q4 stood at S$39.7 million, down 73.5 per cent from S$149.8 million a year ago. Revenue from the sale of properties saw the deepest plunge of 91.4 per cent to S$8.7 million, from S$101.5 million a year ago. This was mainly due to the absence of revenue recognition of residential and commercial units from the Millennium Waterfront project in the current period as these have been handed over in the prior years.
For the full year ended 31 December 2020, net profit was down 38.3% to S$103.2 million, from S$167.1 million a year ago. Revenue was down 36.1% to S$203.9 million, from S$319.2 million.
Earnings per share stood at 0.76 Singapore cent for the quarter, down 93.5% from 11.75 cents a year ago. First Sponsor paid a second interim dividend of two Singapore cents for the full year on 26 February 2021, after the 18 February 2021 record date. Together with the first interim dividend of 1.1 cents paid on 1 October 2020, the total dividend paid for the full year 2020 amounts to 3.1 Singapore cents per share, 14.8% higher than the full year 2019 dividend.
"The group will review its business investment strategy on an ongoing basis to ensure that it remains relevant in the post-Covid-19 new normal," said First Sponsor Group Chief Executive Officer Mr Neo Teck Pheng.
Please click here for First Sponsor’s FY 2020 financial statement.
