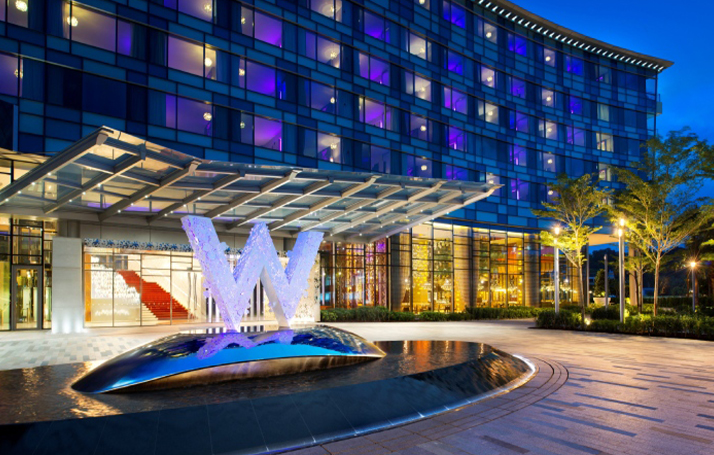
 Following the successful privatisation of Millennium & Copthorne Hotels Limited (M&C) in 2019, the CDL Group is taking a holistic review of its enlarged hotel portfolio to drive synergies. It has taken a more proactive stance as a sponsor to M&C’s listed REIT associate, CDL Hospitality Trusts (CDLHT), with the divestment of the 240-room W Singapore – Sentosa Cove hotel to CDLHT for S$324 million, which was approved by CDLHT unitholders at its EGM in January 2020. The injection of this hotel into CDLHT’s portfolio is an extension of the Group’s commitment to seed suitable hotel assets to support the REIT’s expansion plans.
Hong Leong
Group Of
Companies
Report FY 2019
Results
City Developments Limited (CDL)
Despite a challenging macroeconomic environment, CDL delivered a resilient performance. Profit After Tax and Minority Interests (PATMI) for Q4 2019 rose 12.5% to S$87.7 million and revenue increased 20.1% to S$946.9 million, as compared to Q4 2018.
PATMI for FY 2019 was S$564.6 million, supported by a portfolio with diversified income streams and boosted by the substantial gains from the successful unwinding of CDL’s second Profit Participation Securities (PPS 2) structure with the divestment of Manulife Centre and 7 & 9 Tampines Grande.
Revenue for FY 2019 amounted to S$3.4 billion due to the timing of profit recognition for the property development segment. The Tapestry and Whistler Grand were the main contributing projects where revenue and profits were recognised progressively based on their stage of construction, along with the sale of balance units in completed projects including Gramercy Park, New Futura, Hong Leong City Center (HLCC) in Suzhou and Hongqiao Royal Lake in Shanghai. Comparatively, revenue in FY 2018 was boosted primarily from completed projects including New Futura, Gramercy Park and also The Criterion Executive Condominium (EC) in which its entire revenue was recognised upon obtaining its Temporary Occupation Permit, as well as substantial revenue from overseas projects including HLCC and Park Court Aoyama The Tower in Tokyo.
As at 31 December 2019, the Group has strong cash reserves of S$3.1 billion and Net Asset Value (NAV) per share stands at S$11.60. Notably, the Group adopts the policy of stating investment properties at cost less accumulated depreciation and impairment losses. Had the Group factored in fair value gains on its investment properties, the Revalued Net Asset Value (RNAV) per share would be S$16.46. Net gearing ratio (including fair value gains on investment properties), post privatisation of M&C in October 2019, is 43%.
For more details, click here for CDL’s FY 2019 financial statement.
CDL Hospitality Trusts (CDLHT)
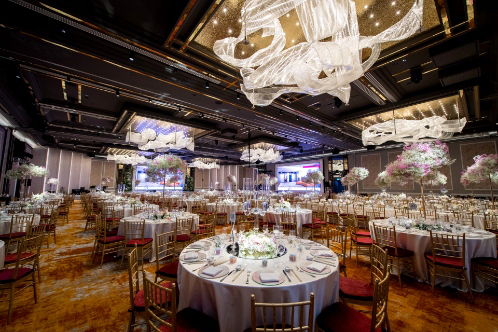 Orchard Hotel Singapore completed major enhancement works in 2019, offering enhanced guest experience.
In Q4 2019, CDLHT’s Singapore Hotels achieved stronger performance with a 5.1% RevPAR (revenue per available room) improvement, the highest quarterly year-on-year RevPAR growth since 2012, on the back of better trading conditions during the quarter. Accordingly, the Singapore Hotels recorded higher Net Property Income (NPI) contribution while Hotel Cerretani Firenze - MGallery, acquired in end November 2018, also provided inorganic support to the overall portfolio NPI.
However, overall NPI for the quarter decreased slightly by 1.2% year-on-year to S$38.0 million as lower contribution from CDLHT’s other overseas properties more than offset growth. A significant portion of the overseas NPI decline was due to the anticipated reduced income from Pullman Hotel Munich, stemming from the cyclicality in the city’s events calendar. Trading conditions in Tokyo (Japan) and Maldives were competitive while contribution from Australia and New Zealand were lower due to a weaker local currency.
For FY 2019, NPI decreased 3.3% to S$141.2 million. Major asset enhancement works at Raffles Maldives Meradhoo and Orchard Hotel Singapore and disruption from renovation works in Angsana Velavaru affected the portfolio’s performance. Absence of major events hosted in Singapore also resulted in lower NPI for the Singapore hotels during the first half of 2019, while the New Zealand, Australia, Japan and UK properties saw lower contribution, in part due to weaker currencies in some of these markets. The collective decline was partially mitigated by the stronger performance of the Singapore Hotels in the second half of 2019 as well as inorganic contribution from Hotel Cerretani Firenze - MGallery and increased NPI for Pullman Hotel Munich.
Total distribution to Stapled Security Securityholders (after retention for working capital) was S$109.4 million, while DPS was 9.02 cents, a decrease of 2.0% and 2.6% year-on-year respectively.
For more details, click here for CDLHT’s FY 2019 financial statement.
Hong Leong Finance (HLF)
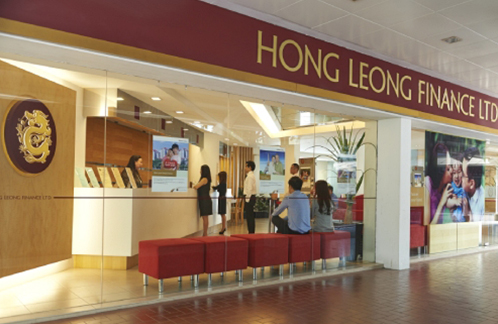 HLF’s net profit decreased 12.9% to S$103.1 million, after accounting for net loss allowance of doubtful debts. Pictured above is HLF’s Clementi West Branch.
HLF posted a net profit of S$103.1 million for the full year ended 31 December, a 12.9% decrease from a year ago, after accounting for net loss allowance of doubtful debts amounting to S$1.6 million, against after a net recovery of doubtful debts of S$2.2 million in 2018.
Earnings per share were 23.09 Singapore cents, down from 26.56 cents in FY 2018.
Its interest income and hiring charges totalled S$396.4 million for the full-year period, up 13.3% from FY 2018, on the back of healthy loan growth and improved loan yields of 16 basis points. Net interest income fell 4.9% to S$201.7 million, driven by higher competitive deposit rates on enlarged deposit base to support the loan growth.
Net loan assets increased 12.4%, or S$1.276 billion, to S$11.554 billion as at 31 December, while deposits and balances of customers also grew 8.5%, or S$994 million, to S$12.307 billion.
For more details, click here for HLF’s FY 2019 financial statement.
First Sponsor Group Limited
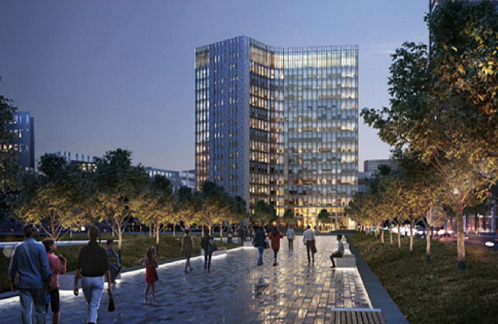 Delivery of the newly developed Oliphant office building (above) in Amsterdam contributed to the Group’s property portfolio.
First Sponsor achieved record pre-tax profit of S$194.2 million for FY 2019, a 34.3% increase from FY 2018. It also recorded a 63.0% quarter-on-quarter growth, achieving net profit of S$94.9 million for Q4 2019.
Income from the Group’s European property portfolio increased 4.7% to S$62.8 million in FY 2019 (FY 2018: S$60.0 million), bolstered by contributions from the delivery of the newly developed Oliphant and Munthof Amsterdam offices, and the Hampton by Hilton Utrecht Centraal Station hotel. Its property financing business in China also achieved a record average loan book of RMB 2.2 billion for FY 2019, up 40% from the previous year’s average of RMB 1.6 billion.
In view of the Group’s strong performance, the Board is proposing a final tax-exempt (one-tier) dividend of 1.6 Singapore cents per ordinary share, a 23.1% increase from FY 2018’s final dividend.
For more details, click here for First Sponsor’s FY 2019 financial statement.
