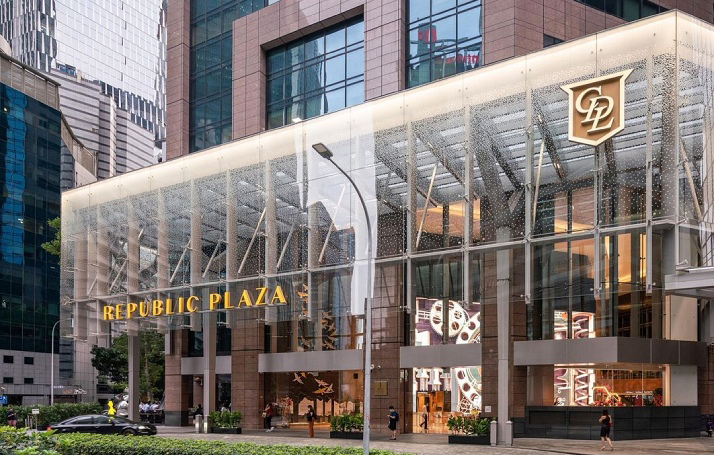
 CDL saw signs of improvements in its core business segments in Q1 2021, but remains wary of impact from the prolonged COVID-19 pandemic.
Hong Leong
Group Companies
Report Q1 2021
Operational
Update
City Developments Limited
In Q1 2021, City Developments Limited’s (CDL) core business segments showed signs of improvement despite headwinds from the prolonged COVID-19 pandemic – where new variant strains are emerging, and subsequent waves of infection remains a concern as it continues to adversely impact operations.
For its property development business segment, CDL achieved a 72% increase in units sold year-on-year in Singapore, while pre-sales for Australia residential projects also saw positive uptake. The committed occupancy of the Group’s Singapore office portfolio remains resilient at 91.4%, above the island-wide occupancy of 88.1%, with positive rental reversion. Despite a lower footfall, gross turnover sales (GTO) of the Group’s malls remain strong, with Q1 2021 GTO registering an increase of over 5% compared to Q1 2020 levels. In addition, the committed occupancy for retail space remains strong at 92.1%, above the island-wide occupancy of 91.5%. For Hotel Operations, global occupancy dropped to 36.8% (Q1 2020: 52.5%) and global RevPAR decreased by 51.7% to S$44.6 (Q1 2020: S$92.4).
The outlook for 2021 remains unpredictable as the COVID-19 situation evolves. Having enhanced digitalisation initiatives last year, CDL is well-prepared to navigate the latest restrictions with agility and flexibly manage the ongoing and inevitable business disruptions across its operations.
While the Group remains watchful of the COVID-19 developments and will embrace these near-term challenges with resilience, to simultaneously continue to shift gears from crisis management back to its core strategy that focuses on Growth, Enhancement and Transformation, with the aim of accelerating growth and recovery while maximising shareholder value.
Please click here for CDL’s full Q1 2021 operational update.
CDL Hospitality Trusts
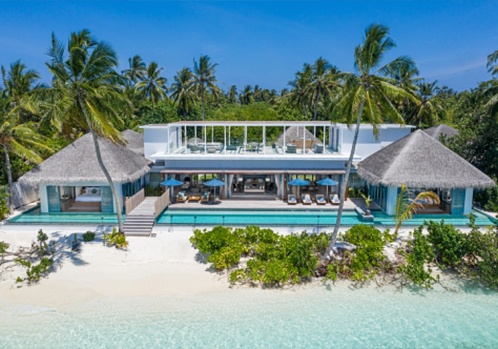 Raffles Maldives Meradhoo, with the opening of its presidential villa in December 2020, saw positive results from its efforts to attract guests from Eastern Europe after an interrupted gestation period.
In Q1 2021, CDL Hospitality Trusts (CDLHT) experienced a year-on-year (yoy) decline in Revenue Per Available Room (RevPAR) for all geographical markets, except for New Zealand and the Maldives, due to the severe impact of COVID-19 on the hospitality industry. However, substantive contributions to its portfolio revenue from its Singapore, New Zealand and Maldives properties, amounting to S$27.6 million (inclusive of S$9.3 million fixed rent), partially insulated the Group from the severe impact of the pandemic. Accordingly, CDLHT’s Net Property Income (NPI) in Q1 2021 increased marginally by 1.0% yoy to S$19.8 million.
In Singapore, borders remain largely closed and market demand remained comprised primarily of government contracts business for isolation purposes, staycations and corporate project groups. Overall, RevPAR for its Singapore hotels fell by 34.3% yoy.
In New Zealand, Grand Millennium Auckland experienced stable occupancy as it continues to serve as a managed isolation facility and RevPAR has trended upwards since Q2 2020.
The Perth hotels received fixed rent for the quarter and the lower NPI was due to the divestment of Novotel Brisbane in October 2020. Going forward, the contribution from the Perth hotels are now exposed to trading conditions as the leases expired on 30 April 2021.
In the Maldives, tourist arrivals picked up in December 2020 and continued into Q1 2021. The Maldives resorts posted a RevPAR growth of 64.1% yoy.
In Japan, tight border restrictions remain in place. Domestic leisure and corporate travel are also significantly curtailed as Tokyo remains under a state of emergency. CDLHT’s Japan hotels saw a 54.2% yoy decrease in RevPAR.
In Europe, fresh lockdowns were imposed in 4Q 2020, which affected the performance of its UK, Germany and Italy Hotels in Q1 2021. Lockdown restrictions in the UK were eased from 17 May 2021 and all holiday accommodation and indoor hospitality venues can reopen. Further easing is expected to take place on 21 June 2021. In Germany, CDLHT finalised the rent restructuring agreement with the lessee of Pullman Hotel Munich, primarily for the purpose of business continuity. The Italy Hotel was closed since October 2020 and has reopened in end-May 2021.
Please click here for CDLHT’s full Q1 2021 operational update.
First Sponsor Group Limited
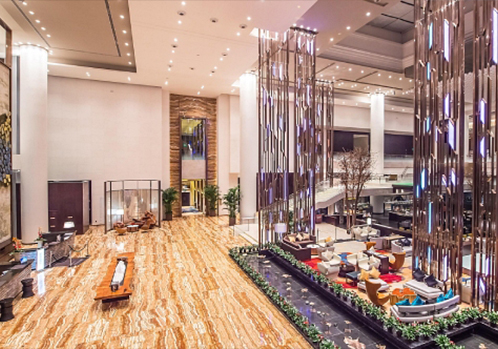 Crowne Plaza Chengdu Wenjiang achieved higher revenue as a result of higher occupancy and average daily rate during the quarter.
First Sponsor saw strong real estate demand in Dongguan, with all residential and SOHO units launched being fully sold. The projects include Star of East River, Emerald of the Orient, The Pinnacle and Skyline Garden. A SOHO cluster comprising 226 units at The Pinnacle will be launched for pre-sale in Q2 2021 and the last residential block at Skyline Garden in Q3 2021.
First Sponsor also decided to acquire 48% interest in a predominantly residential development land in Humen in April 2021, which underscores the Group’s active pursuit of further opportunities in the Greater Bay Area, to capitalise on the positive outlook of the region’s development plan.
Amidst tightened measures to control the spread of COVID-19, the Group’s European hotels achieved an overall loss before interest, tax, depreciation and amortisation (LBITDA) of €4.4 million in Q1 2021. However, its two hotels in Chengdu Wenjiang, China achieved EBITDA of RMB 1.9 million, up from a loss of RMB4.4 million over the same period in 2020.
It’s PRC property financing loan book stood at RMB 2.6 billion as at 31 March 2021.
Please click here for FSGL’s full Q1 2021 operational update.
