Against the backdrop of macroeconomic headwinds clouded with uncertainties, the CDL Group stayed agile and maintained a resilient performance across all its business segments. Below is an update on the Group’s operating performance for the third quarter ended 30 September 2022 (Q3 2022).
Property Development
Singapore
In Q3 2022, CDL and its joint venture (JV) associates sold 95 units with a total sales value of $281 million. Sales were slower for the quarter as the Group has a low inventory of unsold units as its launched projects have been substantially sold, with Sengkang Grand Residences selling out in Q3. Moreover, there were no new launches in Q3.
For the first nine months ended 30 September 2022 (YTD Sep 2022), the Group and its JV associates sold 802 units with a total sales value of $1.9 billion (YTD Sep 2021: 1,382 units with a total sales value of $2.5 billion). However, sales have surged to 1,417 units with a total sales value of $2.8 billion as at 30 November 2022, mainly led by the recent launch of the Group’s JV project, Copen Grand Executive Condominium (EC) in October 2022.
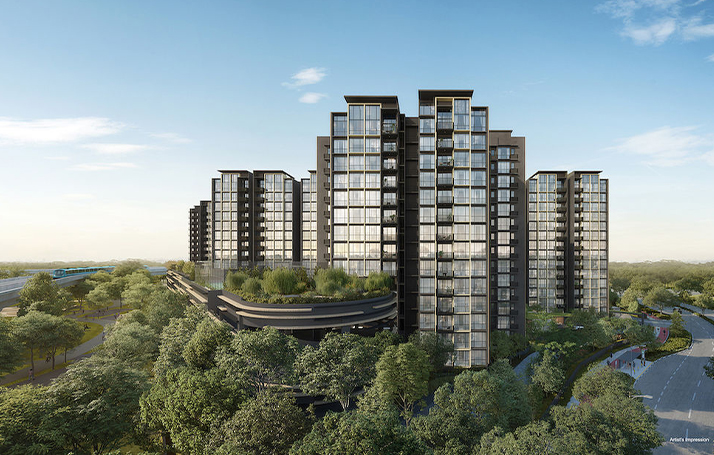
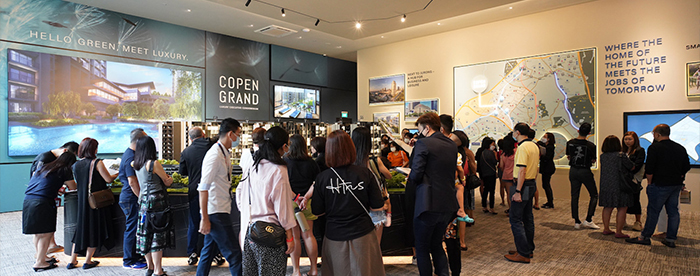
The 639-unit Copen Grand EC opened for e-applications on 7 October and sales bookings commenced on 22 October for eligible buyers. It received a very strong response with 465 units (73% of the project) sold on its launch day. Under prevailing EC regulations, only 30% of the project can be allocated to second-time buyers during launch and the quota was reached.
On 26 November, the Group started sales bookings for second-time buyers who were unable to purchase a unit during the initial launch period. The response was overwhelming with the remaining 146 units snapped up over the weekend, making the project fully sold just one month after its launch.
The average launch price was $1,300 per square foot (psf), with an additional 3% applied to units sold under the deferred payment scheme. Located in the heart of Tengah Town, envisioned to be Singapore’s first smart and sustainable precinct, Copen Grand is within walking distance of three MRT stations on the upcoming Jurong Region Line – a rare attribute for an EC. It will also have convenient access to two neighbouring hubs – the Jurong Lake District and the Jurong Innovation District. The demand for well-located ECs augurs well for the Group’s pipeline EC project in the same vicinity, at Bukit Batok West Avenue 5, which will have around 510 units.
With rising interest rates and inflationary concerns, on 30 September 2022, the Government introduced additional property cooling measures aimed at ensuring prudent borrowing. The reference interest rate used to compute the Total Debt Servicing Ratio (TDSR) and Mortgage Servicing Ratio (MSR) increased by 0.5% from 3.5% to 4.0%. Other measures were more targeted at the HDB market.
With the tightened maximum loan quantum limits for housing loans, potential buyers are likely to be more cautious in their decision-making, mindful of their mortgage servicing capability. Nonetheless, the Group expects the property market to remain resilient given the low stock levels. Moreover, with a recovering economy, Singapore’s political stability, and its strength as a financial hub, there is sustained interest from local buyers, foreign investors and high-net-worth individuals.
To replenish its development pipeline, the Group successfully secured an expansive 178,936 square feet (sq ft) EC Government Land Sales (GLS) site at Bukit Batok West Avenue 5 with a bid price of $336.07 million (or $626 psf ppr) in September 2022. The Group won by a razor-thin margin of 0.2% (or $1 psf ppr) versus the second highest bid. The EC project will comprise 10 blocks of 12 to 13 storeys with around 512 units. The site is conveniently situated between three MRT stations and within the Bukit Batok Nature Corridor.
Australia
In Australia, the Group recently completed The Marker in Melbourne, where 84% of the 198 units have been sold to date. Residents have been progressively moving into the apartments since October. The Group’s purchase of its first Private Rented Sector (PRS) development site in Melbourne’s Southbank was completed in November 2022. Project construction is targeted to commence in Q2 2023 and will yield around 240 units.
Investment Properties
Singapore
As at 30 September 2022, the Group’s office portfolio remained resilient with 94.3% committed occupancy, above the island-wide occupancy of 88.3%. Republic Plaza, the Group’s flagship Grade A office building, is 96.1% committed with a positive rental reversion of 5.9%. The Grade A office market is expected to remain resilient, driven by the limited CBD supply.
The Group’s retail portfolio also remained healthy with 95.3% committed occupancy, above the island-wide occupancy of 92.2%. The robust performance was led by City Square Mall and Palais Renaissance, with a committed occupancy of 98.2% and 100% respectively.
Overseas Markets
China
Multiple lockdowns were imposed due to the emergence of COVID-19 cases which caused disruptions to businesses and negatively impacted sales of the Group’s existing stock. The Group is providing some financial support to its commercial tenants to help them overcome the challenges. The Group continues to hold a positive long-term view of the China property market and is actively looking for new development sites.
UK
London’s office leasing market remained relatively stable, with demand for Grade A energy-efficient buildings as this helps to mitigate soaring energy bills. 125 Old Broad Street and Aldgate House are benefitting from such resilience, providing well-located Grade A offices with enhanced amenities and a robust sustainability strategy. Existing occupiers are renewing their leases, increasing their footprint or in active discussions around a longer-term lease arrangement.
The Living Sector
UK
Limited supply and mortgage affordability issues, exacerbated by higher interest rates in the near term, continue to underpin the rise in rental demand for PRS accommodation in the UK as people turn to renting instead of purchasing homes. This augurs well for The Junction, the Group’s 665-unit PRS development in Leeds, which has begun pre-leasing as its phased completion is on track to commence in Q4 2022.
Japan
The Group’s PRS portfolio in Osaka and Yokohama enjoys stable rent with strong average portfolio occupancy of above 95% for stabilised assets. Demand is fueled by individuals and corporates returning to the workplace, with lesser remote work and a higher propensity to stay within the same prefecture. Employment is normalising to pre-pandemic levels. Restrictions on foreign nationals entering Japan are fully lifted, which should further boost the demand for rental apartments.
Hotel Operations
With the easing of travel restrictions and the pent-up travel demand, the Group’s hotels continued its recovery path, registering a global Revenue Per Available Room (RevPAR) growth of 88.9% to $161.9 for Q3 2022 (Q3 2021: $85.7). For YTD Sep 2022, global RevPAR rose 108.3% to $127.7 (YTD Sep 2021: $61.3), with London and New York improving their RevPAR by 291.2% and 113.3% respectively.
Fund Management
The unprecedented interest rate hikes in 2022 have severely impacted the initial public offerings (IPO) of REITs in Singapore, with several planned IPOs and secondary fund-raising exercises of REITs withdrawn. Amid this challenging market, the Group is placing a temporary pause on its IPO aspirations for its UK commercial properties until the market stabilises. The short-term market uncertainties present opportunities for the Group to make strategic acquisitions that will complement its fund management strategy.
Outlook
Given the global economic uncertainty, unabated inflation and rising interest rates, the outlook remains unpredictable and highly sensitive to market changes. Despite these challenges, the Group continues to accelerate its Growth, Enhancement and Transformation (GET) Strategy, focusing on portfolio growth, strong execution, operational excellence, active capital recycling and driving sustainability initiatives.
The Group’s timely divestments earlier in the year, with the sale of Millennium Hilton Seoul as well as the successful collective sale exercises for Tanglin Shopping Centre and Golden Mile Complex, will provide the Group with adequate financial headroom to deleverage, seek opportunistic investments and maximise shareholder value.
The Group will continue to exercise prudence in its investments and growth plans. By maintaining a robust balance sheet and disciplined capital management, the Group is confident of weathering the storms and emerging stronger.